Golden Shield Life Insurance Resources

Life Insurance Translator

What your quote, application, policy, and illustration are really saying, one line at a time. Written by a licensed agent for the families we serve.

By Aaron Polk, Founder and Licensed Life Insurance Agent, Golden Shield Life Insurance

Woman holding a phone and using the Golden Shield Life Insurance Translator to translate fine print, terminology, and policy language
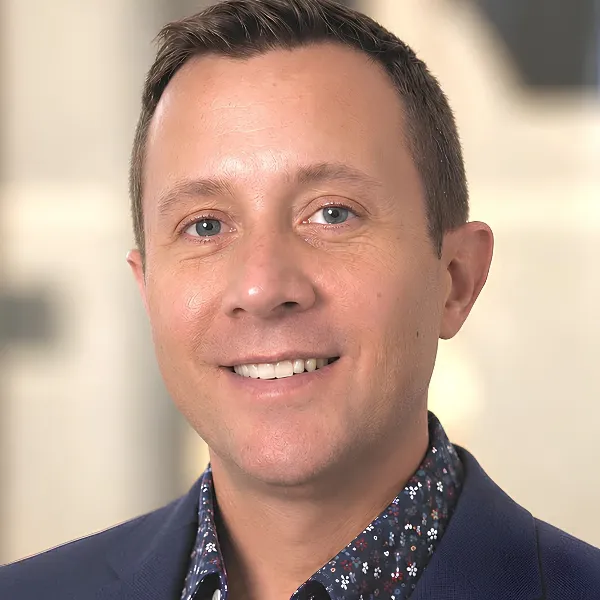
Aaron Polk, founder and licensed life insurance agent at Golden Shield Life Insurance in Atlanta, Georgia

Aaron PolkFounder & CEO

Most of the calls I get after a policy arrives are not about price. They are about one sentence on page four. A client reads “contestable,” “graded,” or “non-guaranteed” and wonders if something went wrong. Usually nothing did. Nobody ever stopped to explain the word.

So this page is how I explain it when we sit down together. Each entry has two parts: what the paperwork says, and what I tell my clients about it. Our Life Insurance Glossary gives you the short definition. This page is about what the word may mean for you and your family.

Sorted by the page you are holdingThe quote, the application, the policy packet, the illustration, the beneficiary form, and the annuity contract.
Taken from real client questionsThese are the words people have actually called us about, not a list copied from a brochure.
A real person behind every answerIf a word still does not make sense, call us. A licensed agent will walk through it with you.

Section 1 of 7

Reading Your Quote

Where you will see these: a price quote or comparison sheet. These words decide what you pay and for how long.

Face Amount

What it saysThe amount the policy is set to pay your beneficiaries when you pass away. Also called the death benefit or coverage amount.

What I tell clientsPick this number by what it needs to cover, like a mortgage, income for your family, or a final expense, not by what sounds like a lot. A loan against the policy can lower what is actually paid out.

Compare Free Life Insurance Quotes

Level Premium

What it saysYour payment is designed to stay the same for a set number of years, or for life on many permanent policies.

What I tell clientsRead how long “level” lasts. A 20-year level term policy usually keeps the same price for 20 years. After that, the price may change a lot.

Term Life Insurance

Post-Level Premium

What it saysThe price you would pay to keep a term policy after its level period ends, often raised every year after that.

What I tell clientsThis number is often buried on the last page of a quote, and it can be many times the original price. If you think you may need coverage longer, ask about a longer term or a conversion option now.

Rate Class

What it saysThe health category the insurance company places you in, such as Preferred Plus, Preferred, Standard Plus, or Standard.

What I tell clientsMost first quotes assume a rate class before anyone has seen your health history. Your final price can move up or down once underwriting is done. Each insurance company draws these lines a little differently, which is one reason we compare several.

Table Rating

What it saysAn extra charge added on top of the Standard rate because of a health condition. You may see it as Table 2 or Table B.

What I tell clientsEach table step often adds roughly 25 percent to the Standard price, though it varies by company. A rating from one insurance company is not the final word. Another company may view the same condition more favorably.

Tobacco Rate

What it saysA higher price class for people who use tobacco or nicotine. Many companies count vaping, nicotine gum, and chewing tobacco too.

What I tell clientsBe honest on this one, because a lab test can show nicotine. Some companies treat an occasional cigar more gently than others, and many look back 12 months or longer before giving non-tobacco rates.

Modal Premium

What it saysThe price for the way you choose to pay: monthly, quarterly, twice a year, or once a year.

What I tell clientsPaying monthly often costs a little more over a full year than paying once a year. Monthly bank draft is still the easiest way for most families to avoid a missed payment.

Section 2 of 7

Applying and Getting Approved

Where you will see these: the application, the phone interview, and approval letters. These words explain how the insurance company decides.

Underwriting

What it saysThe insurance company's review of your health, medications, driving record, and lifestyle to decide whether to offer coverage and at what price.

What I tell clientsThe best thing you can do here is answer every question fully. A missed detail now can cause a delay, a higher price, or a problem with a claim later.

Instant Decision

What it saysAlso called accelerated underwriting. The company uses data checks instead of a medical exam and may approve you in minutes.

What I tell clientsIf you are not approved instantly, that is not a decline. It usually means the company wants more information, such as a phone interview or medical records.

No Medical Exam Term Life

Paramedical Exam

What it saysA short health check, often at your home, where a licensed examiner takes your blood pressure, height, weight, and blood and urine samples.

What I tell clientsSchedule it in the morning, drink water, and skip heavy exercise and caffeine beforehand. Exam results can sometimes earn a better price than a no-exam policy.

MIB Report

What it saysA record kept by MIB, a member organization insurance companies use to share coded information from past insurance applications.

What I tell clientsIt is one reason honesty matters, since a past application may show up. You can generally request your own MIB record for free once a year.4

Prescription History Check

What it saysWith your permission, the company reviews your pharmacy records for the past several years.

What I tell clientsHave your medication list ready before we apply. A prescription you forgot to mention can look like something you hid, even when it was just a short course of medicine.

Simplified Issue

What it saysA policy with health questions but no medical exam.

What I tell clientsIt can be faster, but it may cost more than a fully underwritten policy, and coverage amounts are often lower. Answering “yes” to certain questions can mean you do not qualify.

Life Insurance With No Medical Exam

Guaranteed Issue

What it saysCoverage offered with no health questions, within an eligible age range set by the company.

What I tell clientsIt may be a good fit when health makes other policies hard to get. It usually has a lower coverage limit and a graded death benefit, so I check whether you qualify for something better first.

Guaranteed Issue Life Insurance

Graded Death Benefit

What it saysA waiting period, often the first two or three years, when the full benefit is not paid for a death from natural causes.

What I tell clientsDuring that window, many policies return the premiums paid, often with some interest. Accidental death is usually covered in full from the start. Check your own policy for the exact terms.

Guaranteed Issue Calculator

Approved Other Than Applied For

What it saysThe company approved you, but at a different price, rate class, or coverage amount than you asked for.

What I tell clientsYou do not have to accept it. We can ask why, send more medical information, or compare what another insurance company may offer.

Section 3 of 7

Once Your Policy Starts

Where you will see these: the policy packet that arrives after approval. These words control your rights in the first few years.

Effective Date

What it saysThe date your coverage actually begins, usually once the policy is approved and the first payment is made.

What I tell clientsDo not cancel an old policy until the new one is in force. A short gap in coverage is a risk most families do not need to take.

Free Look Period

What it saysA short window after the policy is delivered when you can cancel and generally get your premium back.

What I tell clientsIt is often at least 10 days, and it may be longer depending on the state, the policy, and whether it replaced another one. Use it. Read the packet and call me with anything that looks off.

Grace Period

What it saysExtra time after a missed payment when the policy stays active, often 30 or 31 days.

What I tell clientsIf you miss a payment, call us right away. Inside the grace period, a late payment can usually fix it with no new health questions.

Lapse and Reinstatement

What it saysA lapse means the policy ended because payments stopped. Reinstatement is the process of bringing it back.

What I tell clientsReinstating often means paying the missed premiums and answering health questions again. Bringing back an older policy can still cost less than starting over at an older age.

Contestability Period

What it saysUsually the first two years of a policy, when the company can review a claim and the original application for missing or wrong information.

What I tell clientsThis is not a reason to worry if your application was complete and honest. It is the best reason I know to slow down and answer every health question carefully.

Exclusion Period

What it saysA clause, often lasting the first two years, saying the full benefit is not paid for certain causes of death, such as suicide.

What I tell clientsIn most of these cases the company refunds the premiums instead. Some policies also list other exclusions, like certain hazardous activities. They are written in the policy, so we read them together.

Conversion Privilege

What it saysThe right to switch a term policy to a permanent one without new health questions, before a deadline set in the policy.

What I tell clientsThis can matter a lot if your health changes. The deadline is often a certain age or a set number of years, so I mark it on your policy summary.

Whole Life Insurance

Section 4 of 7

Living Benefits and Riders

Where you will see these: the rider pages and the benefit summary. These are the parts of a policy that may help you while you are still alive.

Rider

What it saysAn added feature attached to the base policy. Some are included at no extra charge, and some cost more.

What I tell clientsRiders are where two policies at the same price can differ the most. I always check which ones are built in before comparing prices.

Accelerated Death Benefit

What it saysA rider that may let you use part of your death benefit early if you qualify because of a serious illness.

What I tell clientsWhatever you use is subtracted from what your family receives later, often with a fee or discount. It is help during hard times, not extra money.

Living Benefits of Life Insurance

Terminal Illness Rider

What it saysLets you access part of the benefit if a doctor certifies a life expectancy of a limited time, often 12 or 24 months.

What I tell clientsFamilies use this for care, bills, or time together. Many policies include it, but the time limit and the amount vary.

Chronic Illness Rider

What it saysMay pay part of the benefit early if you cannot do two of six activities of daily living, or have a severe cognitive impairment.5

What I tell clientsThe six activities are bathing, dressing, eating, toileting, continence, and moving in and out of a bed or chair. It is not the same as long-term care insurance, but it may help with some of the same costs.

Critical Illness Rider

What it saysMay pay part of the benefit early after a covered diagnosis, such as certain heart attacks, strokes, or cancers.

What I tell clientsThe list of covered conditions is in the rider, and each company writes its own. A standalone critical illness policy is a separate product that pays on top of your life insurance.

Critical Illness Insurance

Waiver of Premium

What it saysIf you become totally disabled and qualify, the company may stop charging your premiums while coverage continues.

What I tell clientsThere is usually a waiting period, often around six months, and an age limit. For a family that depends on one paycheck, I think it is worth a look.

Return of Premium

What it saysA term policy or rider that refunds your base premiums if you outlive the term.

What I tell clientsIt costs noticeably more, and canceling early often means getting back little or nothing. It suits people who will keep the policy the full term and like the idea of a refund.

Section 5 of 7

Cash Value, Whole Life, and IUL

Where you will see these: a policy illustration and your annual statement. These words apply to permanent policies that build cash value.

Cash Value

What it saysMoney that builds inside a permanent life insurance policy over time, separate from the death benefit.

What I tell clientsIt usually grows slowly in the early years because of policy costs. You may be able to borrow against it or withdraw from it later, depending on the policy.

Whole Life Insurance

Cash Surrender Value

What it saysWhat you would actually receive if you canceled the policy today, after surrender charges and any loans.

What I tell clientsThis is the number to watch, not the larger “account value.” In the early years the two can be far apart.

Policy Loan

What it saysBorrowing money from the insurance company using your cash value as collateral.

What I tell clientsInterest is charged, and any unpaid loan is subtracted from the death benefit. If loans grow too large, the policy can lapse and may leave a tax bill, so we review loans every year.

Illustration

What it saysA year-by-year projection of premiums, cash value, and death benefit based on stated assumptions.

What I tell clientsAn illustration is not a promise. It shows one possible path. I always walk you through the low-return column, not just the hopeful one.

IUL Quotes

Guaranteed vs. Non-Guaranteed

What it saysGuaranteed values are the most the policy can charge and the least it can credit. Non-guaranteed values use current rates and costs, which can change.

What I tell clientsIf you can afford the policy using the guaranteed column, you are on solid ground. If it only works in the non-guaranteed column, we should talk.

Cap Rate

What it saysThe most interest an indexed universal life policy can credit in a period, even if the market index rises more.

What I tell clientsCaps are set by the company and can change. Hypothetical example: the index rises 12 percent and your cap is 10 percent. You may be credited 10 percent.

Indexed Universal Life Insurance

Participation Rate

What it saysThe share of the index's gain that is used to figure your credit.

What I tell clientsA higher rate sounds better, but it often comes with a lower cap or a fee. Hypothetical example: the index rises 8 percent with a 50 percent participation rate. Your credit may be 4 percent.

Floor

What it saysThe lowest interest an indexed policy can credit, often 0 percent, even in a year the index falls.

What I tell clientsA 0 percent floor means you are not credited a loss from the index. Policy charges still come out, so your cash value can still go down in a flat year.

MEC (Modified Endowment Contract)

What it saysA policy funded faster than federal tax limits allow, known as the 7-pay test.2

What I tell clientsThe death benefit is generally still income-tax-free, but loans and withdrawals may be taxed and can face a 10 percent penalty before age 59½. We design funding to stay under the limit when that matters to you.

1035 Exchange

What it saysA way to move cash value from one life insurance policy into another policy or annuity without paying tax on the gain at that time.3

What I tell clientsIt can make sense when an old policy no longer fits. New surrender charges and a new contestability period can apply, so I compare both policies side by side first.

Dividend

What it saysA possible payment from certain whole life policies when the company's results are better than expected.

What I tell clientsDividends are not guaranteed. Many families use them to buy more coverage or lower premiums. A long history of paying them is helpful, but it does not promise the future.

Section 6 of 7

Who Gets the Money

Where you will see these: the beneficiary form and the ownership page. A few words here decide who your policy actually protects.

Owner, Insured, and Beneficiary

What it saysThe owner controls the policy. The insured is the person whose life is covered. The beneficiary receives the money.

What I tell clientsThese can be three different people. When they are, taxes and control can work differently, so this is worth a conversation before you sign.

Primary and Contingent Beneficiary

What it saysThe primary beneficiary is paid first. A contingent beneficiary is paid only if no primary beneficiary is living.

What I tell clientsAlways name a contingent. I also suggest reviewing beneficiaries after a marriage, divorce, birth, or death in the family.

Per Stirpes

What it saysLatin for “by branch.” If a beneficiary dies before you, their share passes to their children.

What I tell clientsWithout it, that share may go to your other beneficiaries instead. If you want each child's family covered no matter what, ask whether your form allows per stirpes.

Irrevocable Beneficiary

What it saysA beneficiary who cannot be removed or changed without their written consent.

What I tell clientsThis sometimes comes up with divorce agreements or business deals. Most families are better served by a revocable beneficiary that they can update.

Naming Your Estate

What it saysListing “my estate” as the beneficiary, so the money passes under your will.

What I tell clientsThis can send the money through probate, which may mean delays and exposure to debts. Naming people, or a trust, usually gets money to your family faster.

Naming a Minor

What it saysListing a child under 18 as a beneficiary.

What I tell clientsInsurance companies generally cannot pay a minor directly, so a court may need to appoint someone to manage the money. A trust or a custodian named on the form may avoid that. An estate attorney can help you choose.

Income-Tax-Free Death Benefit

What it saysLife insurance paid because of the insured's death is generally not counted as income to the beneficiary under federal law.1

What I tell clients“Generally” matters. Interest paid on a delayed claim can be taxable, and large estates may still owe estate tax. A tax professional can look at your situation.

Section 7 of 7

Annuity Paperwork

Where you will see these: a fixed annuity contract or rate sheet. These words decide how long your money is committed and how you can reach it.

Guaranteed Rate (MYGA)

What it saysA multi-year guaranteed annuity locks an interest rate for a set number of years, such as three, five, or seven.

What I tell clientsThe guarantee is backed by the insurance company's financial strength, so I look at the company's ratings, not just the rate.

Fixed Annuities Fixed Annuity Calculator

Surrender Period

What it saysThe years when taking out more than the allowed amount triggers a surrender charge.

What I tell clientsOnly put in money you will not need during that time. The charge usually gets smaller each year until it reaches zero.

Free Withdrawal

What it saysThe amount you can take out each year without a surrender charge, often 10 percent of the value.

What I tell clients“Free” means free of the company's charge. Taxes still apply to the gain, and withdrawals before age 59½ may face an IRS penalty.

Annuitization

What it saysTurning your annuity balance into a stream of regular payments, for a set number of years or for life.

What I tell clientsOnce you choose a lifetime payout, the decision is usually permanent. We look at your other income first, including when you plan to claim Social Security.